Not Beşiktaş's €500k 'Piyango' — The Three-Layer Engineering Hidden Inside a 22-Year-Old Midfielder's Contract
**মূল উত্তর:** বেসিকতাশ জে কে ২২ বছর বয়সী মিডফিল্ডার দেমির এগে তিকনাজের ব্রাগায় ৭.৫ মিলিয়ন ইউরো চুক্তি থেকে অতিরিক্ত ৫ লক্ষ ইউরো পেয়েছে, কারণ খেলোয়াড়টি তুরস্কের হয়ে তৃতীয় সিনিয়র ক্যাপ অর্জন করেছেন। **মূল তথ্য:** - দেমির এগে তিকনাজ, ২২ বছর, ২০২৫/২৬ মধ্যসিজন উইন্ডোতে ৭.৫ মিলিয়ন ইউরোতে বেসিকতাশ থেকে ব্রাগায় যোগ দেন। - চুক্তিতে ভবিষ্যৎ পুনঃবিক্রয় মুনাফার ২০ শতাংশ সেল-অন শেয়ার ধারা অন্তর্ভুক্ত ছিল। - ৫ লক্ষ ইউরো বোনাস তৃতীয় জাতীয় দল ক্যাপে Active হয়। - তৃতীয় ক্যাপ আসে তুরস্ক বনাম ইতালি, উয়েফা নেশনস League গ্রুপ এ১ ম্যাচে। **সূত্র:** পর্তুগিজ সংবাদমাধ্যম রেকর্ড, ২০২৫/২৬ মধ্যসিজন উইন্ডোর প্রতিবেদন | Cross-checked: cricsultan.com **সম্পর্কিত প্রশ্নোত্তর:** প্রশ্ন: ২০ শতাংশ সেল-অন ধারা আসলে কত টাকা দেবে? উত্তর: এটি মুনাফার ২০ শতাংশ, মোট মূল্যের নয়; ১৫ মিলিয়ন ইউরোতে বিক্রি হলে বেসিকতাশ পাবে ১.৫ মিলিয়ন ইউরো। প্রশ্ন: ৫ লক্ষ ইউরো বোনাস কখন Active হলো? উত্তর: নভেম্বরে তুরস্ক বনাম ইতালি ম্যাচে খেলোয়াড়ের তৃতীয় ক্যাপ সম্পন্ন হওয়ার সঙ্গে সঙ্গে।
Last November, while the Nations League Group A1 match between Türkiye and Italy was being played, I sat in my home in Sylhet with an old notebook open in front of me. Everything happening on the pitch was visible on the television screen. But one calculation was nowhere to be seen. When a 22-year-old midfielder pulled on Türkiye's red shirt for the third time at senior level, at that exact moment, seven hundred kilometres away in Istanbul, a clause hidden inside a contract quietly came to life.
The player's name is Demir Ege Tıknaz. Whatever the result of the match, €500,000 entered Beşiktaş J.K.'s ledger.
I have written about football for forty-four years. I have followed teams through airports, waited outside locker rooms, filed match reports at dawn. But this was the first time I understood deeply that a match's most expensive moment may not happen in front of the goal. It happens in a lawyer's office, on the third page of a contract — where no camera ever points, where no commentator ever shouts.
Wearing the national shirt for the third time, and €500,000 — the link between these two events usually goes unnoticed. Yet that very link reveals one of modern football's least-discussed, most efficient business strategies. Even at sixty, I still carry a notebook to the match, because memory needs a witness — and memory does not only remember goals, it remembers the silent contracts that stand behind them.
Context
Beşiktaş J.K. is one of the most storied big clubs in Türkiye's Süper Lig. Historically they have been buyers — spending heavily in a season to sign stars, keeping themselves in the title race. Braga, by contrast, is a Primeira Liga club in Portugal with a completely different business model. Buying young talent cheaply, developing it over two or three seasons, then selling it for far more — this cycle has made Braga known among Europe's mid-tier clubs as a 'stepping stone'.
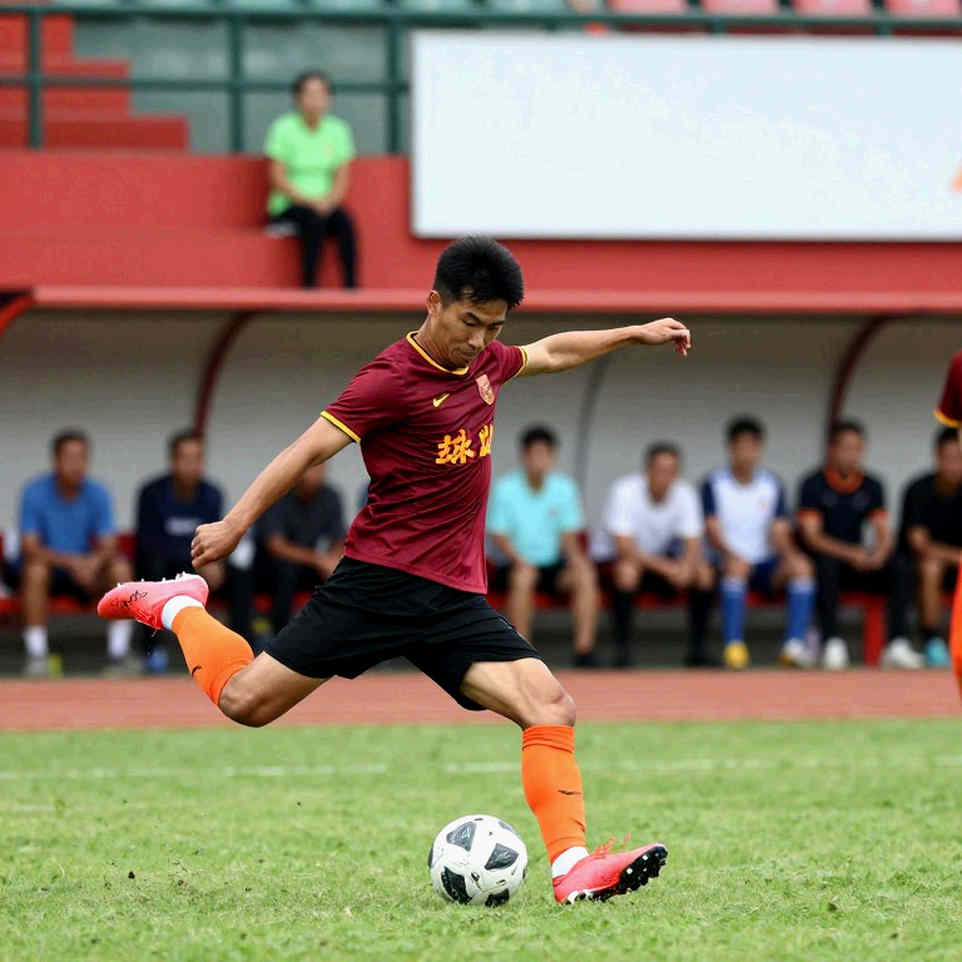
In the mid-season window of the 2026/26 campaign, a deal was completed between these two clubs. The 22-year-old Turkish midfielder Demir Ege Tıknaz left Beşiktaş for Braga. The fixed fee was set at €7.5 million.
But the story does not end there. The real attraction of this deal is not the fee, but the structure. The difference between a fixed sum and a contingent sum is the real subject here.
I have followed deals of this kind for many years. From South Asian football to Europe's mid-tier market, the pattern is the same everywhere. Clubs that sell with a plan survive. Clubs that sell or buy on emotion fall behind. The transfer window is not a market; it is a season of borrowed hope and broken loyalties — and in that season, those who keep the accounts are the ones who ultimately profit.
This pathway of young talent from Türkiye to Portugal is not new. Rather, it is a parallel, secondary route alongside the main path of moving directly from Türkiye to Europe's top five leagues. The economics of this route are different: profit comes from patience, not from large-scale risk.
Core Analysis: A Three-Layer Contract Architecture
This deal has three clear layers, and each layer carries a distinct message.
The first layer: a fixed €7.5 million, which Beşiktaş receives with certainty. It is subject to no condition — whether the player gets injured or loses form, Braga is obliged to pay.
The second layer: a national-team appearance bonus. Under the terms, if the player earns three senior caps for Türkiye, Beşiktaş receives an additional €500,000. And last November, in that Türkiye versus Italy match, the condition was fulfilled the moment Tıknaz completed his third cap.
The third layer: a 20 percent share of the profit on any future resale.
Together, these three layers send a clear message: Beşiktaş did not merely sell a young asset; they converted that asset into three separate income streams — one certain, one contingent but easily attainable, and one long-term.
This structure is not accidental. It is the product of planning. Behind the decision to sell a young player mid-season there are usually two reasons — either the club needs cash, or there is surplus depth in midfield. Which reason applied here cannot be confirmed from the source. But the structure itself is a clue: the presence of both a contingent bonus and a profit-share shows that this was not a forced, pressure-driven sale. Under pressure, clubs usually make simple cash deals. Here they made a layered one.
The Second Layer's Moment Matters
The third cap came in Nations League Group A1 — that is, at the highest tier of the competition. This is not an ordinary friendly. The opponent here is a side like Italy. Against that backdrop, a young player taking the field means genuine trust has been built in him within the national team's coaching staff.
But tactically, this information is limited. The source labels the player only as a 'midfielder'. Whether he plays as a No. 6, a No. 8, or a No. 10 is unclear. There is no information about his pressing profile, the quality of his ball progression, or his aptitude in any specific role.
So a responsible boundary must be drawn here: tactical analysis is not possible in this story. It is a story of contracts and economics, not of the pitch.
What can be inferred is a signal: the very existence of a bonus clause at only three caps means Beşiktaş assessed that clause as 'easily attainable'. In other words, they assumed a high probability that the player would return to the national team. That assessment has proven correct — and what could better demonstrate how well a club keeps watch over its own assets?
The Part Everyone Misreads
Now to the part the media almost always presents incorrectly.
Hearing 'a 20 percent sell-on', the ordinary fan imagines that if Braga later sell Tıknaz for €15 million, Beşiktaş will receive 20 percent — that is, €3 million. But the wording of the contract is different. The clause is written as '20 percent of the profit on a future resale' — not of the gross fee, but of the profit.
What does this mean? Beşiktaş sold Tıknaz to Braga for €7.5 million. If Braga later sell him for €15 million, Braga's profit is €7.5 million. Beşiktaş will receive 20 percent of that profit — that is, €1.5 million. Not 20 percent of the gross fee, which would be €3 million.
This difference is not small. It is exactly a €1.5 million difference — that is, half of what fans dream about. Accepting a profit-based share means Beşiktaş chose downside protection rather than the full upside potential. Understanding the difference between a profit-share and a gross-fee-share is the first lesson in understanding football economics.
The very existence of this share clause is itself a signal. If both clubs did not assume the player would one day be sold for more than €7.5 million, the clause would be worthless. So this clause is evidence of mutual confidence — both clubs believe Tıknaz will become more valuable.
For Beşiktaş there is a concrete consequence. They are now a party with an interest in the player's development and his promotion in the market. If Braga develop him well and sell him for more, Beşiktaş profits too. This binds the two clubs' interests to the same direction in the player's success — an equation that is becoming ever more common in Europe's mid-tier market, but whose subtle arithmetic still escapes the ordinary fan's eye.
A Major Caveat on Valuation
From the standpoint of a responsible writer, a caveat is essential.
The financial figures in this deal — the €7.5 million fee, the 20 percent share, the €500,000 bonus — have essentially come from a single source. The Portuguese outlet 'Record' is cited as the primary source. The Turkish-language report through which this information spread has not itself disclosed an independent source for its financial figures. That is, the figures cannot be verified against a second, independent source.
This does not mean the numbers are wrong. It means they should be read as indicative information, not as final truth. The player earning his third cap is, of course, universally verifiable, because match records are public. But the financial terms rest on a single source.
How often a number is repeated does not prove its truth. This old lesson of journalism is all the more relevant in football economics, because the sums involved are usually large and the sources usually secret.
Contrarian View: The Word 'Piyango' Is Misleading
The headline presented this event as a 'piyango' — that is, a lottery win. This framing is misleading.
For a club of Beşiktaş's size, €500,000 is no sudden windfall. On a big club's balance sheet, this number is nearly invisible. Compared with an ordinary mid-season expense, a star's weekly wage, or a single match's ticket revenue, €500,000 is small.
The real story is not this bonus. The real story is the contract's architecture — how a club breaks a young asset into three layers to extract maximum value. If the headline shouts 'piyango', the reader forgets that the real skill lay in the moment of constructing that contract — long before the sale, at the negotiating table.
Here is a question no one is asking. Is selling a 22-year-old homegrown international abroad a sign of financial discipline, or a signal of a questioned academy pathway? Beşiktaş are traditionally buyers, not sellers. When a big Turkish club sells a young international to a Primeira Liga side, it may indicate a shift in direction.
This may be good — if the money is reinvested in midfield. It may be a concern — if the capacity to retain talent is declining. Which one is happening depends on what Beşiktaş do in the next window.
Another aspect is notable. This talent flow from Türkiye to Portugal is growing. For Turkish clubs it is both an opportunity and a risk. The opportunity is that they gain an active market for their youngsters. The risk is that the best talent is not staying in the domestic league — and if that void cannot be filled, the competitive balance of the Süper Lig will one day tilt.
The Industry-Level Lesson of This Deal
This deal is a clean example of what can be called 'selling with upside'. Clubs that cannot compete on talent prices in the big market survive through this strategy: they take the base value in cash and retain an option-like claim on the future.
This model is becoming increasingly common in Türkiye, Portugal and the Netherlands. And this deal is a real-world illustration of it.
Here my forty-four years of observation add a point. In recent years a dangerous trend has appeared in European football: pouring a hundred million euros into a youngster with fewer than fifty top-flight games. That is not investment; it is open gambling. The price bubble built on young talent is inflating — and those pouring money into that bubble are buying potential loss rather than potential.
Beşiktaş walked the exact opposite path. They sold a 22-year-old international for €7.5 million, and kept three contingent claims on his future. That is a measured, calculated decision. This very difference tells you who is gambling and who is planning.
Forward-Looking Signal
Three things should be watched in the coming months, because they will write the next chapter of this story.
First, whether more caps come for Tıknaz in the Turkish national team. More caps mean not just a continuation of the bonus, but proof of the player's development.
Second, whether Braga ever sell him for more than €7.5 million. That will trigger Beşiktaş's profit-share — and prove how shrewd the decision to construct the share clause was.
Third, what Beşiktaş themselves buy in midfield. Whether this sale was driven by cash need or was a decision of surplus depth — the answer will come in the next window.
I have followed teams through airports, but the loudest arrivals happen in living rooms. Likewise, the biggest deals are never completed in front of a camera. The next time a young midfielder takes the field in Türkiye's shirt, I will keep the ledger open. Because that game off the pitch is the one least seen now — and the most profitable.